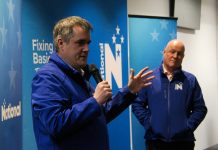
The Prime Minister is to make his annual pre-budget speech today.
By any estimate, it will be a hard ask.
There must be a big question mark whether he will be able to greet this year’s Budget with the smile he did last year.
In a preview yesterday, the ANZ Bank put the challenge to write the Budget succinctly when it said it would be hard to put together because there were no easy options.
What the ANZ didn’t say was that not only is Finance Minister Nicola Willis under extraordinary pressure because of the Middle East War, but as a poll published last night shows, her party is still struggling to get a clear ascendancy in the polls as we approach the election in November.
Its biggest problem shows up in yesterday’s Curia Taxpayers Union poll, with New Zealand First still not far off doubling its vote from the 2023 election.
That doesn’t mean the coalition cannot hold Government after the election, but it does suggest that the coalition negotiations are going to be much trickier than last time.
National will be anxious to try and increase its support now to make those negotiations later easier.
But how?
The usual answer in an election year is for the Government to spend up in its Budget.
That is what the National Party did in the last election year it faced as a Government in 2017.
It set the Budget operating allowance at $1.8 billion, up from $1.6 billion the year before.
Put those figures into the Reserve Bank Inflation calculator, and $1.8 billion becomes $2.4 billion in 2026 money – exactly what the operating allowance for this Budget already is.
The Wellington social and economic issues consultancy, Martin Jenkins, has produced its own Budget preview and has focused on the operating allowance.
Its author, Aaron Gabbie, says that this year’s operating allowance is lower than the $3.2 billion in Budget 2024, and a lot lower than the $5.9 billion in Budget 2022 at the tail-end of the COVID-19 response.
“In that light, $2.4 billion appears to be tight, including in the context of the oil-driven economic shock,” he says.
“In fact, it hasn’t been that low for the best part of a decade. But look back further, and the picture is different.
“Low operating allowances were common following the Global Financial Crisis, when early economic stimulus soon changed to fiscal restraint to reduce debt.
“The negative allowance in 2011, one of Bill English’s Budgets, was nicknamed the ‘zero Budget”
“The allowance began to increase from about Budget 2016, when GDP was growing at a solid 4% per year.
“The allowance peaked with the tail-end of the pandemic response and Budget 2022, which saw the Treasury forecast deficits over the next four years.
“Budget 2022 followed massive economic support provided by way of a COVID fund, which allocated $58.4 billion to a range of initiatives.”
That Budget had the Government’s books returning to surplus this year.
In the 2023 Budget, the surplus shifted out to 2026.
In 2024, it shifted to 2028, and then last year, it first went to 2029, but then in December, Treasury changed that forecast to 2030.
Now, the ANZ Bank believes this year’s Budget will show it shifting out again beyond 2030.
If that happens, Willis can expect to come under fire this Budget over the ever-elusive return to surplus.
The Government’s problem is that they don’t know what the impact of the Middle East war will be, since no one really knows what its prognosis is likely to be.
The ANZ summarises the challenge facing the Government: “Budget 2026 will be delivered against a challenging economic backdrop, with the oil price shock squeezing balance sheets, eroding confidence, and weighing on economic activity and employment.”
“There are no easy policy options: broad‑based fiscal stimulus would add to inflation pressures, putting more pressure on the RBNZ to raise interest rates, ultimately rendering fiscal stimulus ineffective overall while pushing public finances further towards unsustainable territory,” the Bank said.
“Fiscal policy can take the edge off for the most vulnerable, but it cannot do so for everyone.”
The ANZ sees Willis’s recent revelation that Treasury was redoing its forecasts as significant.
“Given the lack of resolution in the Middle East conflict, this suggests the assumptions underpinning their original outlook were on the optimistic side, just as our initial assumptions proved to be!” the BZ said.
“Based on our own forecast revisions since December, we expect the Treasury is likely to shave around $30bn from its nominal GDP forecast to June 2030, with much of the associated fiscal impact relatively front‑loaded.
“Like us, the Treasury will need to make assumptions about the timing of a potential resolution to the Middle East conflict and its implications for the domestic and global economy.”
The Reserve Bank is scheduled to publish a Monetary Policy Statement and make an Official Cash Rate announcement the day before Willis presents her Budget.
How that timing came about is a mystery, but it means we will be confronted with two substantial forecasts of the economy by two different organisations within 24 hours of each other.
It is also curious because it would be usual for the Budget forecasts, particularly the level of stimulation it might apply to the economy, to be of critical importance to the Reserve Bank.
The ANZ argues that it might be best if Willis opts for an even tighter budget than the operational spending allowance provides for.
“One could argue that for the long-run health of the economy, it would be better to tighten discretionary fiscal settings now (i.e. increase taxes and/or reduce spending),” the Bank said.
“That would alleviate pressure on the RBNZ to hike, reduce the risk that Government debt exceeds the Treasury’s estimate of prudent levels, and reduce the risk of a Sovereign ratings downgrade (which would add to borrowing costs across the entire economy).”
But, as it concedes, “democracy doesn’t always reward long-term thinking, particularly at times of near-term stress.”
That is the balance that Willis must reach: between economic responsibility and her obligation to her party to give them something they can use in the election campaign.
And so: “Budget 2026 will be framed largely as a crisis‑response Budget, with much of the focus on balancing the need to support vulnerable households while avoiding putting additional pressure on medium-term inflation,” the Bank said.
“From a structural perspective, the Budget Update forecasts are likely to show that New Zealand is only one more shock away from fiscal settings creeping outside prudent levels – and that’s before considering the longer-run fiscal challenges associated with an aging population.
“The question then becomes what to do about that – make the hard choices or keep riding that shortened road towards an eventual sharp, painful but inevitable adjustment.”
Gabbie can draw on Martin Jenkins intimate knowledge of the inside of many Government entities when he questions whether the $5 billion-plus of savings that Willis found from Covid and other spending in the last budget can be found again?
“It’s difficult to identify potential savings initiatives at that scale without significant policy changes,” he said.
“Finding savings of more than a couple of hundred million dollars from one initiative is unusual, and we’ve seen few examples of this in recent history.”
So the Prime Minister today will need to emphasise that this Budget will be in no position to offer any easy answers; if he doesn’t do that, he could run the risk of having to let the electorate’s expectations down before the election.
With the polls as tight as they are, he won’t want to do that — surely?